Building a home is a different kind of loan. We make sure it is set up for the build.
A construction loan is paid out in stages as the house goes up, not in one lump sum. Getting the lender, the contract and the timing lined up before you start saves stress, delays and money.
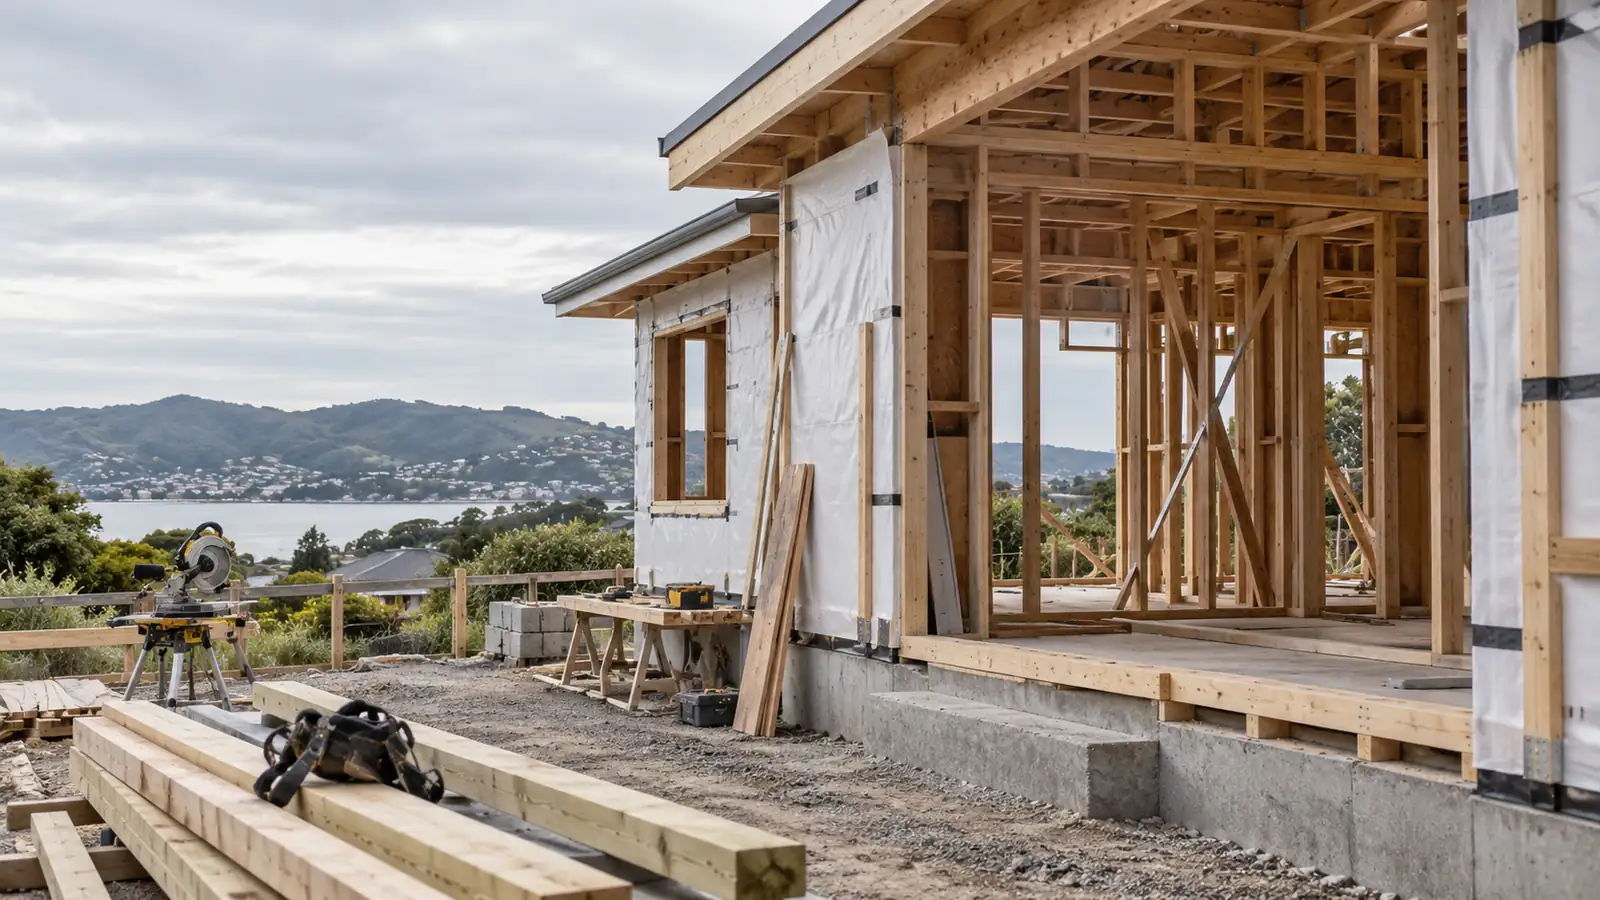
Whether you are building on land you own, buying a house-and-land package, or knocking down and rebuilding, the lending works differently from buying an existing home. Not every lender does it well, and each one has its own rules about builders, contracts and payments.
How a construction loan works
The lender approves the full amount up front, but pays it out in stages as the build progresses. These are called progress payments, or drawdowns. Each one is usually released after the builder invoices and, for many lenders, after a valuer or quantity surveyor confirms the work is done.
During the build you generally pay interest only on the amount drawn so far. Full repayments start once the house is finished and the loan converts to a standard mortgage.
What lenders look at
- The contract. Most lenders prefer a fixed-price contract with a registered builder. Some will consider other arrangements, such as labour-only or managing the build yourself, but fewer lenders do, and the terms are stricter.
- The builder. Lenders want to know who is building, their track record, and whether a builder's guarantee or warranty is in place.
- The value on completion. A valuer assesses what the finished home will be worth, based on the plans and specifications. That value, not the build cost, often decides how much you can borrow.
- Your buffer. Builds can run over time and over budget. Lenders look for a contingency, and so should you.
The common routes
Land you already own
If you own the section, its value can often count towards your deposit. The lending then covers the build.
House-and-land packages
You buy the land and sign a build contract at the same time, often with a group home builder. The timing of the land settlement and the first progress payment needs to be planned together.
Knock down and rebuild
You keep the land and replace the house. The lender will look at how you will manage during the build, including where you live and whether any existing lending needs to be restructured.
Building your first home
Some lenders treat new builds more favourably, and there may be options with a smaller deposit.
How we help
- We check the contract before you sign. From a lending point of view, so there are no surprises when it reaches the lender.
- We choose a lender that suits the build. Some lenders handle construction far better than others. We match the lender to your builder, contract and timing.
- We plan the payments. Deposit, land settlement, progress payments and any contingency, mapped out before work starts.
- We stay with you through the build. If something changes on site, we help you work through what it means for the loan.
When to talk to us
Before you sign a build contract or buy the land. That is when there is still time to get the lending right. The first conversation is free, with no obligation.
Common questions.
How is a construction loan different from a normal mortgage?
The lender approves the full amount up front but pays it out in stages as the build progresses. These are called progress payments. Once the house is finished, the loan becomes a standard mortgage.
Do I need a fixed-price contract?
Most lenders prefer one, with a registered builder. Some will consider other types of contract, but fewer lenders do and the terms are usually stricter.
Do I pay interest during the build?
Usually you pay interest only on the amount drawn so far. Full repayments start once the build is complete.
Can the land count towards my deposit?
If you already own the land, its value can often count towards your deposit. The lender will look at its value and any lending already secured against it.
What clients say about working with Carl.
Carl was an absolute pleasure to work with. His knowledge, professionalism and prompt communication gave us confidence throughout our first home purchase. He secured us an excellent deal with Westpac and made the entire process seamless. We highly recommend Carl to anyone looking for a mortgage broker.
Three of us, all self employed, wanted to get a home loan for a shared house. Without the expertise, help and the precise instructions to fill in the various documents or organise specific items we would not have had a chance to get the mortgage over the finish line. Carl was extraordinarily helpful and always found a way to continue this not so easy application. I can highly recommend Carl. Very grateful for his assistance.
Carl was fantastic to work with. Our mortgage application was not straightforward as we were multiple people, all self employed with new businesses. We had tried using other brokers but they weren't able to get our approval across the line. Carl was tenacious with the banks, and had so much knowledge he was able to guide us through all the information we required and how to present it. After a difficult process he was able to secure us a mortgage with very favourable terms. I couldn't recommend him enough, the effort and work he puts in is second to none!
Carl Mann is a fantastic mortgage broker. He is knowledgeable, professional, and has excellent communication. Carl kept us updated along the way and provided sound advice. I would definitely recommend Carl to anyone needing assistance with mortgage finance or refinancing.
Carl helped us work through the finance for our next investment property without losing sight of our existing lending. He understood what we were trying to build over the longer term and worked through the different options with us before we made an offer. That preparation made the purchase much smoother.
Development finance was very different from arranging a normal mortgage. Carl understood the feasibility, valuations, build costs and timing the lender needed to see, and helped us get everything organised before it went to credit. Having someone who understood the development side of the deal saved a lot of back and forth.
We were purchasing premises for our business and needed someone who could look at both the property and the strength of the business behind it. Carl worked through the numbers with us, explained what the lenders would focus on and helped structure the application properly from the start.
Start with a conversation.
Tell us about the build: the land, the builder and your timing. We'll work out the lending that fits.
Every conversation is confidential.
Book a conversation